The Jupiter Assets Wealthy Buyers Still Want
One thing I keep thinking about in Jupiter is how a distinctive property can serve more than one purpose when the world feels uncertain.
Most people look at a house as a place to live. At the higher end, some buyers also consider how a property fits into a broader ownership and asset-allocation plan. That is a personal decision, not a guarantee of preservation, appreciation, liquidity, or performance.
That is the part that makes Jupiter interesting.
Cash feels safe, but it is not perfect. Inflation is a general increase in prices over time, which can reduce the purchasing power of a fixed nominal amount of cash when prices rise 1. Bonds have interest-rate risk: bond values generally change when market interest rates change 2. Stocks can move sharply based on company results, political or market events, headlines, and other factors 3.
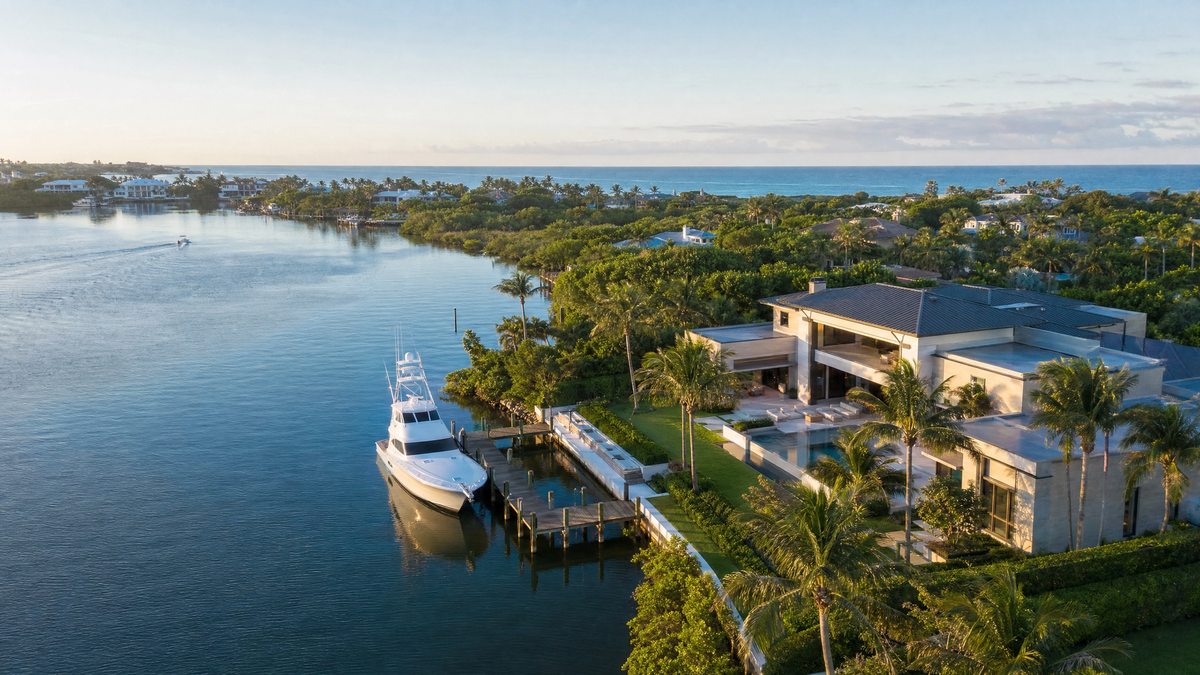
A waterfront property is a tangible, usable asset, but its value and liquidity depend on the specific location, improvements, carrying costs, market conditions, and financing. It is not automatically safer or more advantageous than financial assets.
If the location, waterfront characteristics, improvements, and ownership costs fit the buyer's objectives, the property may offer a combination of personal use and control that a financial asset does not. Those benefits have to be weighed against maintenance, insurance, taxes, financing, regulatory, and resale considerations.
That does not mean every expensive home is a great asset. Some are simply large homes with large carrying costs. Some may be priced above what a buyer considers justified by the location or improvements. Buyers should evaluate the specific property rather than assume that a high price means rarity.
In my experience, some buyers evaluate high-end properties for both lifestyle use and long-term ownership. Current buyer behavior should be assessed with dated local transaction data, not broad assumptions about what wealthy buyers are doing.
For a particular property, replacement difficulty should be evaluated using its parcel, waterfront characteristics, zoning, permitted improvements, and comparable inventory. Some Jupiter waterfront properties offer dockage, privacy, and boating access, but availability and tax or insurance costs vary materially by property and should be verified from current listings, public records, and applicable authorities.
When a buyer has substantial liquidity, deciding how much capital to hold in cash or allocate elsewhere is a personal financial decision. At some point, capital needs a home. For some buyers, a Jupiter property may serve both a personal-use objective and a broader asset-allocation objective, subject to independent financial and tax advice.
Some buyers may place greater value on tangible, usable property during periods of uncertainty, but the effect on demand and pricing is market- and property-specific. Nothing about a property guarantees that it will rise in value, preserve wealth, or be easy to sell.
The buyer is not always just buying a house. Sometimes the buyer is assessing whether a particular property can serve the family's intended use and fit the buyer's broader plan. That assessment should be grounded in property-specific diligence, current market evidence, and professional advice where appropriate.
That is the part of the market I am paying closest attention to right now: not what is merely expensive, but what is genuinely suitable for the buyer's objectives.